A car can make work, family obligations, and everyday errands easier, but the monthly payment is only one part of the financial picture. Before choosing a vehicle, shoppers should look at the full cost of ownership, from fuel and insurance to maintenance, taxes, and resale value. Drivers comparing options and features can learn more while keeping a practical ownership budget in view.
The goal is not simply to find a vehicle that fits today’s payment. It is to choose one that remains manageable through changing fuel prices, routine service visits, unexpected repairs, and the eventual decision to trade or sell. Building that broader view before shopping can prevent a stressful budget surprise later.
What Car Ownership Really Costs
Total cost of ownership includes every expense connected to buying, operating, protecting, and eventually replacing a vehicle. Some costs are fixed, such as a loan payment or insurance premium. Others change with driving habits, including gasoline, charging, tires, tolls, parking, and repairs. A driver with a $450 payment may still spend hundreds more each month to keep the vehicle on the road.
Depreciation also matters, even though it does not arrive as a bill. It is the difference between what the vehicle costs to buy and what it is worth when sold or traded. For a useful benchmark, annual driving-cost estimates can help shoppers remember to account for more than financing alone.
How To Build A Realistic Car Budget
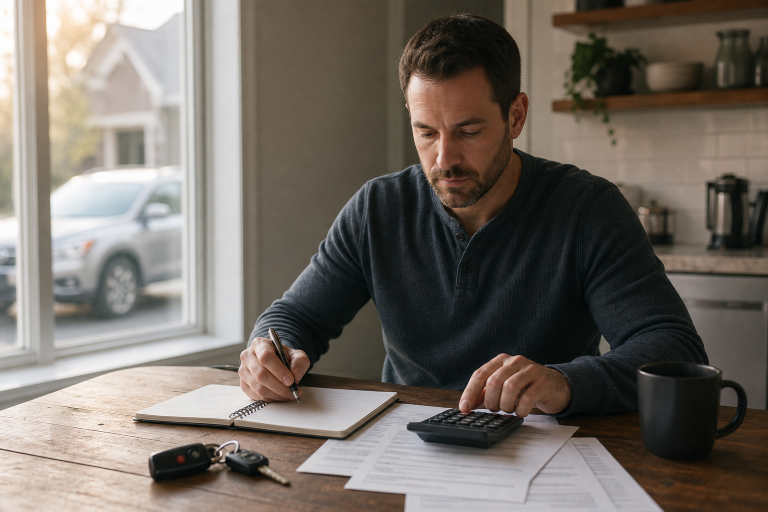
Start with monthly take-home income, then subtract housing, food, utilities, debt payments, savings goals, and other household essentials. The amount left should cover all vehicle expenses, not just the amount due to a lender.
- Estimate how many miles you expect to drive each month.
- Get insurance quotes for the specific vehicles under consideration.
- Set monthly amounts aside for fuel or charging, routine service, and repairs.
- Add registration, taxes, parking, and tolls where applicable.
- Keep a separate emergency repair fund instead of using the down payment as the entire cash cushion.
Questions To Ask Before Shopping
- Will the vehicle mainly handle commuting, family trips, city errands, or towing?
- Would a smaller vehicle meet the same daily needs?
- Can the household absorb a higher insurance premium?
- Is dependable home or workplace charging available for an electric vehicle?
- How long do you realistically plan to keep the vehicle?
The Main Costs To Track
Depreciation
Age, mileage, condition, accident history, local demand, and service records all influence resale value. Two vehicles with similar purchase prices can have very different depreciation patterns. A vehicle with strong demand and a documented maintenance history may preserve more value, while a poorly maintained model can become harder to sell.
Fuel Or Electricity
Compare energy costs using annual mileage, not only an advertised miles-per-gallon figure. Stop-and-go traffic, cold weather, aggressive acceleration, cargo weight, and underinflated tires can reduce efficiency. Electric vehicles can lower fuel spending for some households, but charging equipment, public charging habits, electricity rates, and trip planning still belong in the calculation.
Insurance, Maintenance, And Repairs
Insurance rates vary by location, driving history, coverage level, deductible, vehicle value, theft risk, and repair complexity. Request quotes before buying, then compare both the premium and the amount you would need to pay after a claim.
Routine maintenance includes tires, brakes, fluids, filters, batteries, wiper blades, and scheduled inspections. Unexpected repairs are separate. Modern cameras, sensors, and driver-assistance features can make collision repairs more involved, so maintaining a repair reserve is wise even for newer vehicles.
Taxes, Registration, Parking, And Tolls
Location can dramatically change the ownership equation. A large vehicle may be convenient in a suburban driveway but expensive in a city with paid parking, garages, congestion charges, or frequent toll roads. Compare the out-the-door price, rather than the advertised price, because sales tax, registration, documentation charges, and add-ons affect the amount financed.
How Vehicle Type Changes Long-Term Costs
Small cars and sedans often use less fuel, cost less to park, and may need less expensive tires. Crossovers and SUVs provide cargo room, passenger space, ground clearance, and available all-wheel drive, but their added weight and larger tires can raise operating costs. The most economical choice is often the smallest vehicle that comfortably meets real needs.
Hybrids may make sense for drivers who cover many city miles, while electric vehicles can be appealing for households with reliable charging and predictable travel patterns. Neither choice is automatically cheaper for everyone. Purchase price, insurance, battery coverage, local repair availability, and daily driving habits all matter.
Why Preventive Maintenance Matters
Following the manufacturer’s service schedule helps catch small issues before they become costly failures. Check tire pressure, fluid levels, battery condition, and warning lights promptly. Keep paper or digital service records, especially if you plan to sell later. An inspection before a long trip or seasonal weather change can protect both reliability and resale value.
New Versus Used: Which Choice Fits The Budget?
A new vehicle can offer factory warranty protection, current safety features, and more predictable early maintenance. A used vehicle may have a lower price, less exposure to the sharpest initial depreciation, and a wider range of options within a fixed budget. Neither is always the better deal.
For a used vehicle, review the history report, service records, tire and brake condition, and signs of water or collision damage. Before completing the purchase, use the VIN to check for open safety recalls and arrange an independent inspection whenever possible.
How To Keep Financing Costs Under Control
Compare loan offers before visiting a seller, and focus on the total amount paid over the life of the loan. Review the interest rate, loan term, required down payment, and any fees. A longer term can lower the monthly payment while increasing total interest and raising the chance that the loan balance exceeds the vehicle’s value. Also, review the contract for optional products that may have been added to the financing agreement.
A Simple Car Ownership Cost Worksheet
Copy this list into a notes app or spreadsheet and total the amounts monthly:
- Loan or lease payment: $_____
- Fuel or charging: $_____
- Insurance: $_____
- Maintenance reserve: $_____
- Repair reserve: $_____
- Registration and taxes: $_____
- Parking and tolls: $_____
- Estimated depreciation: $_____
- Total monthly ownership cost: $_____
Common Questions
What Is The Biggest Hidden Cost?
Depreciation is often the biggest overlooked expense because it reduces vehicle value quietly over time.
Is A Used Vehicle Always Cheaper?
No. It may cost less upfront, but it could need more repairs, tires, brakes, or catch-up maintenance.
How Much Should A Driver Save For Maintenance?
Set aside an amount based on the vehicle’s age, mileage, warranty status, service history, and expected tire costs.
Final Takeaway
A smart car budget accounts for the entire ownership experience. When depreciation, insurance, energy costs, maintenance, repairs, financing, and location-based expenses are considered together, drivers can choose a vehicle that feels affordable both now and years down the road.